INTERNATIONAL,JS- Improving a credit score in Canada can help consumers strengthen their financial profiles and prepare for future borrowing. Whether someone plans to apply for a credit card, finance a vehicle, secure a mortgage, or access a personal loan, a stronger credit history can improve their chances of qualifying for suitable financial products.
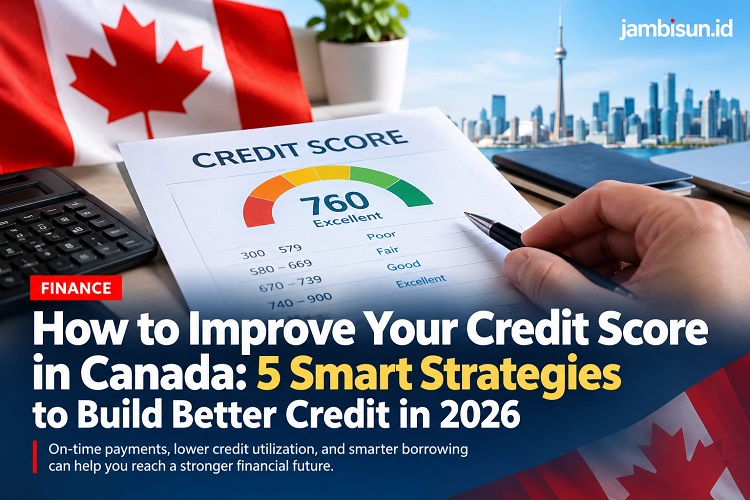
Canada’s two major credit bureaus, Equifax Canada and TransUnion Canada, maintain consumer credit information and generate credit scores. Many Canadian credit scoring models use a range of 300 to 900, although the exact scoring system and rating categories can vary by lender and scoring model.
Consumers often consider scores of 660 or higher a useful benchmark for good credit, while scores around 760 and above generally indicate a stronger profile.
The good news is that consumers can take practical steps to strengthen their credit profiles. Consistent payments, responsible credit card use, a longer credit history, and fewer unnecessary credit applications can all help.
Here are five strategies Canadians can use to improve their credit scores and manage their borrowing more effectively in 2026.
1. Pay Every Bill on Time to Build a Strong Credit History
Payment history plays an important role in credit scoring. Lenders want to see whether borrowers consistently meet their financial obligations, including credit card payments and loan instalments.
Even one missed payment can create problems, especially when the account remains overdue for an extended period. Depending on the creditor’s reporting practices and the scoring model, late payments can affect a credit profile for years.
For that reason, consumers should make payment deadlines a priority.
Set Up Automatic Payments
Automatic payments can help prevent missed deadlines. Consumers can arrange recurring payments through their bank accounts or credit card providers, where available.
At a minimum, schedule enough money to cover each account’s required payment by the due date. Paying the full statement balance whenever possible offers an additional benefit because it can help avoid interest on purchases under the card’s applicable terms.
However, automatic payments only work when sufficient funds remain in the linked account. Consumers should monitor their balances and review scheduled withdrawals regularly.
Pay at Least the Minimum Amount Due
When money becomes tight, paying the minimum amount by the deadline can help maintain a positive payment record.
Although minimum payments do not eliminate interest charges or reduce debt quickly, they generally offer a better alternative to missing a payment entirely.
Consumers should also contact their lenders early if they anticipate financial difficulties. Some lenders may offer payment arrangements or other assistance, depending on the circumstances.
Resolve Billing Disputes Without Ignoring Deadlines
A disputed charge does not automatically remove a consumer’s payment obligation. Anyone challenging a credit card transaction or another bill should contact the provider promptly and ask about the applicable dispute process.
This approach helps borrowers address billing problems without unnecessarily increasing the risk of late payments.
2. Keep Credit Card Balances Low
Credit utilization measures how much revolving credit a consumer uses compared with the total available credit limit.
For example, someone with a $10,000 credit limit and a $4,000 balance has a utilization ratio of 40%.
A lower ratio generally supports a healthier credit profile. Many financial experts recommend keeping utilization below 30%, although consumers with stronger credit profiles may benefit from keeping it lower.
Importantly, 30% does not represent a universal cutoff. Different scoring models assess credit utilization differently, and no single ratio guarantees a particular score.
Calculate Your Credit Utilization
Consumers can calculate their utilization ratio by dividing their credit card balances by their total available credit limits and multiplying the result by 100.
Consider someone who holds two credit cards with a combined limit of $10,000. If their combined balances total $2,000, their utilization stands at 20%.
Reducing those balances to $1,000 would bring utilization down to 10%, assuming the available limits remain unchanged.
This calculation gives borrowers a straightforward way to monitor their credit card usage and identify opportunities to reduce balances.
Pay Down Balances Before the Statement Closes
Credit card issuers may report account information to credit bureaus at different times. Consequently, the balance that appears on a credit report may differ from the amount a consumer currently owes.
Consumers who want to lower reported utilization can consider making an additional payment before the statement closing date.
However, they should first check their card issuer’s reporting practices because the reporting date may not match the payment due date.
Most importantly, consumers should focus on reducing actual debt rather than moving balances between accounts without addressing the underlying amount owed.
Consider a Credit Limit Increase Carefully
A higher credit limit can reduce utilization when the balance stays the same. For instance, a $2,000 balance represents 20% utilization on a $10,000 limit but only 10% on a $20,000 limit.
Nevertheless, requesting an increase may involve a credit inquiry, depending on the issuer’s process. Consumers should ask whether the provider will conduct a hard inquiry before submitting a request.
A higher limit also creates a greater temptation to spend. Therefore, borrowers should pursue an increase only when they can maintain disciplined spending habits.
3. Keep Older Credit Accounts Open When Practical
The length of a consumer’s credit history can influence credit scoring. Older accounts may help demonstrate a longer record of managing credit responsibly.
For this reason, consumers should carefully consider the consequences before closing an established credit card, particularly when the account has no annual fee and remains easy to manage.
Closing a card can reduce total available credit and increase utilization if the consumer continues to carry balances elsewhere.
However, keeping every account open does not always make financial sense. An expensive annual fee, fraud concerns, poor service, or difficulty controlling spending may justify closing an account.
Consumers should compare these costs against the potential benefits of maintaining an older account.
They should also remember that credit history calculations vary by scoring model. Closing an account does not necessarily erase its historical information immediately, and consumers should avoid assuming that every closure will produce the same result.
The main objective is to maintain a stable credit history while choosing financial products that suit current needs.
4. Avoid Too Many Credit Applications in a Short Period
Every application for a new credit card or loan can affect a credit profile differently, depending on the lender’s process and the type of inquiry.
A hard inquiry may occur when a lender checks a consumer’s credit report to evaluate a new application. Several hard inquiries within a short period can concern some lenders and may temporarily lower a credit score.
Consumers can reduce unnecessary inquiries by researching eligibility requirements, comparing product terms, and applying only when they have a clear reason to seek additional credit.
Compare Loan Offers Strategically
Consumers shopping for a mortgage or vehicle loan should ask lenders or brokers how credit inquiries work during the comparison process.
Some scoring models group qualifying inquiries for certain types of loans within a defined shopping period. However, the treatment depends on the scoring model, loan category, and timing.
A two-week window may apply in some circumstances, but consumers should not assume that every credit application within that period will count as a single inquiry.
Planning applications carefully can help consumers compare financing options while limiting unnecessary credit checks.
Check Your Own Credit Report
Checking your own credit report generally counts as a soft inquiry and does not lower your credit score.
Consumers can review their reports through Equifax Canada and TransUnion Canada. Regular checks can help identify incorrect account details, unfamiliar applications, or possible fraudulent activity.
Correcting an error does not guarantee an immediate score increase, but accurate reporting helps lenders evaluate a consumer’s credit history more fairly.
5. Build a Healthy Mix of Credit Products
Credit mix refers to the different types of credit a consumer manages. Examples include revolving credit, such as credit cards and lines of credit, and instalment credit, such as car loans and personal loans.
Some scoring models consider credit mix when evaluating a consumer’s profile. However, consumers do not need to borrow money unnecessarily just to add another type of credit to their records.
Taking out a loan creates repayment obligations, interest costs, and potential financial risks. A new account can also generate a hard inquiry and affect the average age of a consumer’s accounts.
Instead, consumers should focus on managing their existing accounts responsibly.
Someone who already has a credit card and an instalment loan may have a varied credit profile without opening additional accounts. Someone with limited credit history may benefit more from building a consistent payment record than from pursuing multiple products at once.
Consider a Secured Credit Card
A secured credit card can help people with limited credit histories or damaged credit records establish or rebuild their profiles.
With this type of card, the consumer provides a security deposit, and the issuer generally sets the credit limit based on its terms. The cardholder then uses the account and makes payments much like a regular credit cardholder.
Before applying, consumers should confirm that the issuer reports account activity to Equifax Canada, TransUnion Canada, or both.
They should also compare annual fees, deposit requirements, interest rates, and eligibility conditions.
A secured card does not guarantee credit score improvement. However, responsible use and consistent payments can help establish a stronger record over time.
How Long Does It Take to Improve a Credit Score in Canada?
The time required to improve a credit score depends on the consumer’s starting position, payment history, outstanding balances, and the information lenders report.
Some consumers may see changes after their creditors report lower balances. Others may need several months or longer to demonstrate consistent repayment behaviour.
People recovering from missed payments or serious credit problems may need more time because negative information can remain on their credit reports for years, depending on the type of record and applicable provincial rules.
Consumers should therefore avoid promises of instant score increases. Instead, they should monitor their reports, pay bills consistently, reduce outstanding balances, and avoid unnecessary borrowing.
They should also remember that the score displayed by a bank or credit monitoring service may differ from the score a lender uses when reviewing an application.
Common Mistakes That Can Hurt Your Credit Score
Even consumers with good financial intentions can make decisions that weaken their credit profiles.
One common mistake involves paying only the minimum amount indefinitely. Although minimum payments can help prevent missed-payment records, they may leave consumers carrying expensive debt for longer.
Another mistake involves maxing out credit cards, even when the cardholder makes every payment on time. High utilization can still affect credit scoring.
Consumers should also avoid applying for multiple cards simply to access promotional offers. Each application should serve a clear financial purpose.
Finally, closing older accounts without considering their fees, available limits, and account history can create unintended consequences.
A better approach combines careful borrowing decisions with regular financial reviews.
Conclusion
Improving a credit score in Canada requires consistent financial habits rather than a single quick fix.
Consumers can strengthen their credit profiles by paying bills on time, keeping credit card balances low, maintaining suitable older accounts, limiting unnecessary credit applications, and managing their existing credit products responsibly.
They should also review their Equifax Canada and TransUnion Canada reports regularly to identify errors and monitor changes.
Although no strategy guarantees a specific score or loan approval, these practical steps can help Canadians build a stronger credit history, improve their financial readiness, and make more informed borrowing decisions in 2026.(*)