INTERNATIONAL,JS- Refinancing a mortgage in the United States can help homeowners reduce monthly payments, adjust loan terms, or access cash from their home equity. However, the decision requires careful financial planning because a new mortgage comes with closing costs, interest charges, and eligibility requirements.
In October 2026, homeowners need to compare available interest rates, review their credit profiles, and calculate potential savings before replacing an existing home loan. A lower advertised rate does not automatically guarantee a better financial outcome.
The right refinancing strategy depends on several factors, including the outstanding mortgage balance, the remaining loan term, the homeowner’s credit score, and plans to stay in the property.
US Mortgage Refinance Rates in October 2026
Mortgage refinance rates in the United States fluctuate according to market conditions, lender pricing, borrower creditworthiness, and loan characteristics. The interest rate that one homeowner receives may differ significantly from another homeowner’s offer.
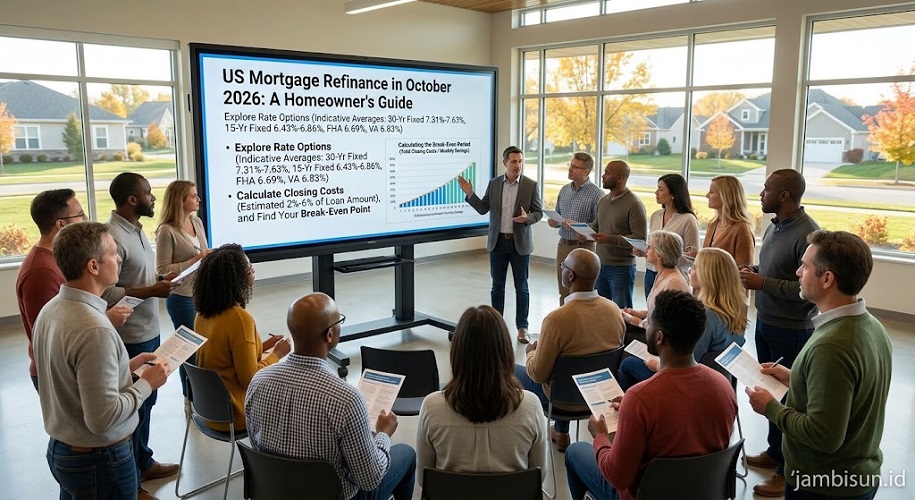
The following figures represent the indicative national averages supplied for October 2026. They serve as estimates rather than verified live quotes, and borrowers should confirm current offers with lenders before making a decision.
| Mortgage Loan Type | Indicative Interest Rate |
|---|---|
| 30-year fixed-rate mortgage | 7.31%–7.63% |
| 15-year fixed-rate mortgage | 6.43%–6.86% |
| FHA 30-year mortgage | 6.69% |
| VA 30-year mortgage | 6.83% |
These figures assume a strong borrower profile and may not reflect the terms available to every applicant. Actual refinance offers can vary based on credit scores, loan-to-value ratios, property types, discount points, and lender requirements.
For example, a homeowner with an excellent credit history may qualify for a more competitive offer than someone with missed payments or substantial outstanding debt. Therefore, borrowers should request personalized quotes instead of relying exclusively on national averages.
Why Homeowners Consider Mortgage Refinancing
Mortgage refinancing replaces an existing home loan with a new mortgage. Homeowners generally pursue this option to achieve one or more financial objectives.
1. Lower Monthly Mortgage Payments
A lower interest rate can reduce monthly principal and interest payments when other loan terms remain comparable.
However, borrowers should examine the complete loan structure. Extending a mortgage from 15 years to 30 years may reduce the monthly payment even when the interest rate changes very little. That arrangement can also increase the total interest paid over the life of the loan.
2. Change the Mortgage Term
Some homeowners refinance from a 30-year mortgage to a 15-year loan to repay their debt faster.
A shorter term usually requires higher monthly payments, but it can reduce lifetime interest expenses. This strategy may appeal to borrowers with stable incomes who want to build home equity more quickly.
Conversely, homeowners facing higher living expenses may prefer a longer term to improve monthly cash flow.
3. Access Home Equity
A cash-out refinance allows homeowners to replace their existing mortgage with a larger loan and receive the eligible difference in cash.
For instance, a homeowner with a property worth $450,000 and an outstanding mortgage balance of $250,000 has $200,000 in gross home equity before transaction costs and other obligations.
A lender may allow the homeowner to borrow against part of that equity, subject to loan-to-value limits, credit requirements, and financial qualifications.
Homeowners sometimes use the proceeds for home improvements, debt consolidation, or other major expenses. Nevertheless, they should consider the risks before converting unsecured debt into debt secured by their homes.
Mortgage Refinance Closing Costs: How Much Should You Prepare?
Refinancing involves several transaction expenses. Depending on the lender, property, loan amount, and state, closing costs may range from approximately 2% to 6% of the new loan amount.
Consider a homeowner who plans to refinance a $300,000 mortgage. Using that estimated range, the potential closing costs would total $6,000 to $18,000.
The actual amount may fall outside this range, so borrowers should request a Loan Estimate and review the itemized charges before committing to a new mortgage.
Common expenses include:
Lender origination fees: Lenders may charge fees to process and underwrite the new loan. The amount depends on the lender and the loan agreement.
Home appraisal: An appraiser may evaluate the property’s current market value. Costs can range from approximately $300 to $1,000, depending on the property and location.
Title search and title insurance: These expenses cover title-related checks and applicable insurance requirements. Costs may range from $300 to $2,000.
Credit report fees: Lenders review a borrower’s credit history and financial profile. Credit-related charges vary, although the supplied estimate places them below $30.
Other expenses may include recording fees, prepaid property taxes, homeowners insurance, and prepaid interest. Some borrowers also pay discount points to obtain a lower interest rate.
Importantly, a lender’s no-closing-cost refinance does not necessarily eliminate the expenses. The lender may offset those charges through a higher interest rate or add them to the loan balance.
Three Types of Mortgage Refinancing in the US
Homeowners should understand the main refinancing options before comparing lender offers.
Rate-and-Term Refinance
A rate-and-term refinance changes the mortgage interest rate, loan duration, or both without primarily focusing on withdrawing home equity.
This option may suit homeowners who can secure better terms than their existing mortgage offers.
For example, a borrower with a high-rate mortgage may reduce interest expenses by refinancing at a lower rate. However, the borrower should compare closing costs and the remaining repayment period before proceeding.
Cash-Out Refinance
A cash-out refinance replaces the existing mortgage with a larger loan and provides eligible cash proceeds from the difference.
This option can help homeowners finance renovations or cover substantial expenses. However, it increases or restructures the debt secured by the property.
Borrowers should compare a cash-out refinance with alternatives such as a home equity loan or home equity line of credit (HELOC). Each option has different fees, interest structures, repayment requirements, and risks.
FHA and VA Streamline Refinancing
Certain homeowners with existing Federal Housing Administration (FHA) or Department of Veterans Affairs (VA) mortgages may qualify for streamlined refinancing programs.
These programs can simplify parts of the application process when borrowers meet the relevant requirements. Depending on the program and circumstances, lenders may waive a new appraisal or request less documentation.
However, streamline refinancing does not guarantee approval, eliminate every closing cost, or ensure a lower overall borrowing expense. Homeowners should verify program eligibility and compare the financial benefits with their current mortgage.
How to Calculate the Mortgage Refinance Break-Even Point
One of the most important steps involves calculating how long the monthly savings will take to recover the refinancing costs.
The break-even formula is straightforward:
Break-even period (months) = Total closing costs ÷ Monthly mortgage savings
Suppose a homeowner pays $6,000 in refinancing costs and reduces the monthly mortgage payment by $200.
The calculation produces the following result:
$6,000 ÷ $200 = 30 months.
In this example, the homeowner needs 30 months, or two and a half years, to recover the initial refinancing expenses through monthly payment savings.
If the homeowner expects to sell the property before that period ends, refinancing may not deliver enough financial value under these assumptions.
However, the break-even calculation only provides a starting point. It does not account for every difference in loan balances, tax treatment, interest accumulation, or the effect of extending the repayment term.
Borrowers should also compare total interest expenses and the remaining mortgage balance under both loan options.
Example: Comparing Refinancing Costs and Monthly Savings
The following examples illustrate how closing costs and monthly savings affect the break-even period.
| Closing Costs | Monthly Savings | Break-Even Period |
|---|---|---|
| $3,000 | $150 | 20 months |
| $6,000 | $200 | 30 months |
| $9,000 | $250 | 36 months |
| $12,000 | $300 | 40 months |
The figures represent hypothetical scenarios, not lender quotes or guaranteed savings.
A homeowner who expects to remain in the property for five years may have more time to recover refinancing costs than someone who plans to move within one year.
Even so, a shorter break-even period does not automatically make a new mortgage the best choice. The borrower should also compare the total cost of borrowing and the amount of equity retained in the property.
How Credit Scores Affect Mortgage Refinance Offers
Credit scores play an important role in mortgage refinancing. Lenders may use credit history, debt obligations, income, and other underwriting factors to assess risk and determine loan terms.
Borrowers who want competitive offers should review their credit reports before submitting applications. Correcting inaccurate information, paying bills on time, and reducing revolving credit balances may help strengthen their applications over time.
However, these steps do not guarantee a particular interest rate or approval.
Homeowners should also review their debt-to-income ratio, which compares monthly debt obligations with gross monthly income. Lenders may consider this measure alongside employment, assets, property value, and available equity.
Requesting Loan Estimates from multiple lenders can help borrowers compare interest rates, lender fees, discount points, and projected monthly payments on a consistent basis.
When Does Mortgage Refinancing Make Financial Sense?
Mortgage refinancing may offer meaningful benefits when the new loan supports a clear financial objective and the homeowner expects to recover the associated costs.
A homeowner may benefit when a lower interest rate reduces total borrowing expenses, a shorter term supports faster repayment, or a cash-out transaction meets a carefully evaluated financial need.
On the other hand, refinancing may provide limited value when closing costs outweigh the expected savings, the homeowner plans to move soon, or the new loan substantially extends the repayment period.
Borrowers should also examine whether the refinance changes mortgage insurance obligations or introduces prepayment penalties and other contractual costs.
Before signing the final documents, homeowners should compare the existing mortgage with the proposed loan under realistic assumptions. They should evaluate monthly payments, total interest, closing costs, the remaining principal balance, and their expected length of homeownership.
Final Takeaway
Mortgage refinancing in the United States can help homeowners restructure their debt, manage monthly payments, or access home equity. However, the decision requires more than finding a lower advertised interest rate.
In October 2026, borrowers should verify current lender offers, compare refinancing fees, review their credit profiles, and calculate the break-even period before proceeding.
The most suitable mortgage is not necessarily the one with the lowest monthly payment. Instead, homeowners should prioritize a loan that fits their budget, repayment goals, and expected time in the property while keeping the overall cost of borrowing under control. (*)