INTERNATIONAL,JS- China’s online personal loan market has undergone a major transformation as regulators tightened financial oversight and shut down the country’s traditional peer-to-peer (P2P) lending industry. Today, consumers seeking digital credit must navigate a system that relies on licensed banks, regulated consumer finance companies and technology platforms that work with financial institutions.
For borrowers, this shift changes how online loans work, who can qualify and which risks deserve attention before submitting an application.
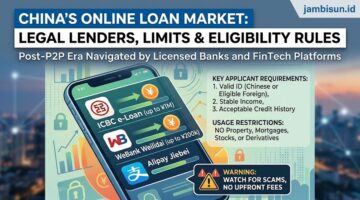
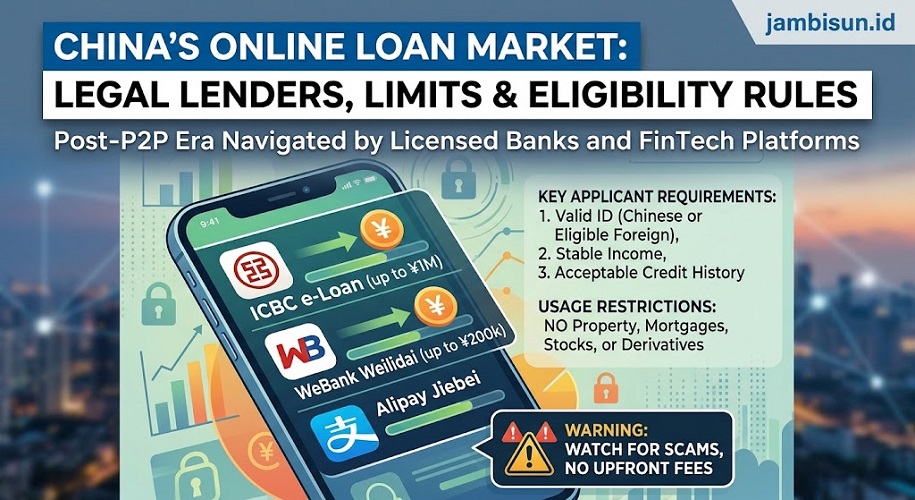
Several options remain available to eligible customers, including ICBC e-Loan, WeBank’s Weilidai and Ant Group’s Jiebei. However, these services do not offer universal access. Eligibility, credit limits, interest rates and repayment terms depend on the lender, the applicant’s financial profile and the product’s current conditions.
China’s P2P Lending Crackdown Changed the Market
China once hosted thousands of online lending platforms that connected individual lenders with borrowers. The model expanded rapidly because digital services offered convenient access to credit outside traditional banking channels.
However, fraud, failed platforms, fundraising risks and borrower losses prompted authorities to strengthen supervision.
By the end of 2020, China had closed or transformed all operating traditional P2P lending platforms, according to regulatory statements and industry reports. This marked a significant turning point for the country’s online finance sector.
The shutdown did not eliminate digital lending. Instead, banks and licensed financial institutions took a more central role in providing online credit.
As a result, consumers should distinguish between legitimate digital loan products and unlicensed websites that advertise instant cash without meaningful checks.
1. ICBC e-Loan Offers Unsecured Personal Credit
Industrial and Commercial Bank of China (ICBC), one of the country’s largest commercial banks, offers ICBC e-Loan as an unsecured personal credit product.
According to ICBC’s official product information, eligible borrowers can access a credit limit of up to RMB 1 million, with repayment terms of up to five years under the product’s stated conditions.
Applicants can use ICBC’s digital banking channels to check eligibility and submit applications. The bank assesses each application before deciding whether to approve the loan and determining the applicable terms.
Nevertheless, the maximum advertised limit does not guarantee that every applicant can borrow RMB 1 million. The bank considers its eligibility requirements, income information and other relevant risk factors.
ICBC also requires borrowers to use the funds for legitimate purposes that comply with the loan agreement. The product excludes certain uses, including property purchases, mortgage repayment and investments in stocks, bonds, futures or financial derivatives.
Prospective borrowers should review the bank’s current terms before applying because eligibility criteria and available services may vary by customer and location.
Official source: https://www.icbc-ltd.com/ICBC/EN/PersonalFinance/PersonalLoan/PersonalCreditLoan/personalcreditloan.htm
2. WeBank’s Weilidai Provides Digital Microloans
WeBank, a digital bank associated with Tencent, operates Weilidai, a consumer credit service integrated into the WeChat ecosystem for eligible users.
The service allows qualifying customers to access credit through supported digital channels without visiting a conventional bank branch for every stage of the process.
Some published product descriptions have cited credit limits of up to RMB 200,000. However, borrowers should confirm the current limit, interest rate, repayment schedule and eligibility conditions directly through the official service.
Weilidai does not guarantee approval simply because someone uses WeChat. The provider evaluates customer eligibility and determines the credit terms it can offer.
Users should also check the total repayment amount rather than focusing only on the advertised borrowing limit. Interest charges, repayment frequency and the loan period can significantly affect the overall cost.
For anyone considering a digital loan, these details matter more than the speed of the application.
3. Alipay’s Jiebei Connects Eligible Users With Credit
Ant Group’s Jiebei service offers another digital borrowing option within the Alipay ecosystem.
The service provides credit to eligible users through supported arrangements with financial institutions. Availability and product conditions can depend on the user’s account, credit assessment and the relevant lending provider.
Although some descriptions associate Jiebei eligibility with Zhima Credit, users should not assume that a single score automatically guarantees approval. Lenders may consider several factors, including credit history, financial circumstances and internal risk assessments.
Applicants should read the loan agreement carefully before accepting an offer. They should identify the actual lending institution, understand the applicable interest rate and confirm the repayment deadline.
A familiar payment application does not remove the need to assess borrowing costs or verify the lender’s identity.
Who Can Apply for an Online Personal Loan in China?
China’s personal lending rules recognize both Chinese citizens and eligible foreign individuals, subject to applicable requirements. However, individual lenders can impose additional conditions, and many digital products primarily serve established domestic customers.
Applicants generally need to demonstrate several important qualifications.
Valid identification: Lenders may request a Chinese resident identity card or, where permitted, a passport and valid residence documentation.
Stable income: Employment records, salary information, bank statements or other financial documents can help lenders evaluate repayment capacity.
Acceptable credit history: Lenders may examine records in China’s financial credit information system, alongside their own assessment criteria.
Repayment capacity: Applicants should demonstrate that their income can support the proposed monthly payments without creating excessive financial pressure.
Local eligibility: Some products require a qualifying domestic banking relationship, an eligible residence or employment location, and access to a supported digital account.
Foreign nationals should not assume that a Chinese work visa or residence permit automatically qualifies them for an online personal loan. They should contact the relevant bank or licensed lender to confirm the documentation and application process.
China’s Personal Loan Management Measures also recognize eligible foreign individuals under applicable rules. Nevertheless, the lender retains responsibility for verifying the applicant’s circumstances and deciding whether to approve the application.
How Much Can Borrowers Receive?
Online personal loan limits vary considerably across providers and applicants.
ICBC e-Loan publishes a maximum limit of RMB 1 million, while some descriptions of Weilidai cite limits of up to RMB 200,000. These figures represent product-level ceilings, not guaranteed offers.
A lender may approve a much smaller amount after assessing an applicant’s income, existing debts, credit history and repayment capacity.
Borrowers should compare the annual interest rate, repayment period, fees and total amount payable. A larger credit limit does not necessarily make a loan more affordable.
For example, a borrower who chooses a longer repayment period may face lower monthly payments but could pay more interest over the life of the loan. The actual result depends on the lender’s pricing and repayment structure.
Before accepting an offer, applicants should calculate whether the instalments fit comfortably within their monthly budget.
Where Can Borrowers Use the Money?
Personal credit products generally require borrowers to follow the purposes stated in their loan agreements.
ICBC’s published conditions specifically restrict the use of its personal credit loan for property purchases, mortgage repayment and certain financial investments.
Borrowers should not assume that every personal loan permits unrestricted spending. Each lender may impose specific conditions based on the product and applicable regulations.
Applicants should check whether their intended expense qualifies before accepting the funds. Misusing a loan can violate the agreement and trigger contractual consequences.
They should also avoid relying on personal credit to finance speculative investments. Investment losses can leave borrowers with outstanding debt even when the value of the purchased asset falls.
China Tightens Oversight of Digital Lending
China continues to strengthen supervision of online lending and bank partnerships with internet platforms.
In April 2025, the National Financial Regulatory Administration published new requirements for commercial banks’ internet-assisted lending businesses. The rules emphasize stronger bank management, reasonable pricing, risk controls and consumer protection. The measures took effect on October 1, 2025.
These requirements highlight an important principle: digital convenience should not replace responsible lending standards.
Banks and their partners must pay attention to loan pricing, risk assessment and the responsibilities of institutions involved in the lending process.
For consumers, stronger oversight makes it especially important to identify the actual lender behind an online loan offer rather than relying solely on a technology company’s brand.
How to Avoid Online Loan Scams
Borrowers should verify the lender before sharing personal information or accepting a loan offer. Scammers often exploit the demand for fast credit by promising guaranteed approval or unusually large limits.
Watch for these warning signs:
- Upfront payment demands: Be cautious if a supposed lender requires a processing fee, deposit or tax payment before releasing funds.
- Guaranteed approval: Legitimate lenders assess applications and do not guarantee approval to everyone.
- Unclear interest rates: Avoid offers that conceal the annual rate, fees or total repayment amount.
- Unverified applications: Use official banking applications and websites rather than unfamiliar links sent through messages.
- Requests for sensitive credentials: Never disclose banking passwords, verification codes or other security credentials to an unknown party.
Borrowers should also check the repayment schedule and consequences of late payment before signing an agreement.
What Borrowers Should Know Before Applying
China still offers digital personal credit, but the market no longer operates like the traditional P2P lending sector that once connected individual lenders and borrowers.
ICBC e-Loan, Weilidai and Jiebei illustrate how banks and technology-linked financial services provide credit through digital channels. However, each product has its own eligibility rules, limits and costs.
Applicants should verify the lender’s legal identity, review the latest terms and calculate the full repayment obligation before making a decision. Foreign residents should confirm their eligibility directly with the provider rather than relying on general online descriptions.
Ultimately, the safest approach is to borrow only what you can repay, use the funds for permitted purposes and avoid any service that promises effortless approval without proper verification.
Frequently Asked Questions
1. Are P2P lending platforms still operating legally in mainland China?
China closed or transformed all operating traditional P2P lending platforms by the end of 2020. Digital lending continues through other regulated arrangements, including licensed financial institutions.
2. Can foreigners apply for online personal loans in China?
Some lending rules recognize eligible foreign individuals, but access depends on the lender and product. Foreign applicants should confirm the required identification, residence documents and other conditions directly with the provider.
3. Does ICBC e-Loan offer RMB 1 million to every applicant?
No. RMB 1 million represents the published maximum limit. ICBC determines each applicant’s eligibility and approved credit amount.
4. Can borrowers use personal loans to invest in stocks or cryptocurrency?
ICBC’s published terms prohibit using its personal credit loan for specified financial investments, including stocks, bonds, futures and financial derivatives. Borrowers must follow the restrictions in their own loan agreements.
5. What should borrowers check before accepting a digital loan?
Confirm the lender’s identity, annual interest rate, fees, repayment period, total repayment amount and permitted use of funds. Avoid services that demand suspicious upfront payments or promise guaranteed approval.
Conclusion
China’s online personal loan market now operates under a stricter regulatory framework following the exit of traditional P2P platforms. Banks and eligible digital credit providers continue to offer borrowing options, but approval depends on individual circumstances and the lender’s requirements.
Consumers can make better financial decisions by checking official product information, comparing borrowing costs and choosing repayment terms that match their income. Careful verification remains essential, especially when an online offer promises quick access to large sums of money.(*)